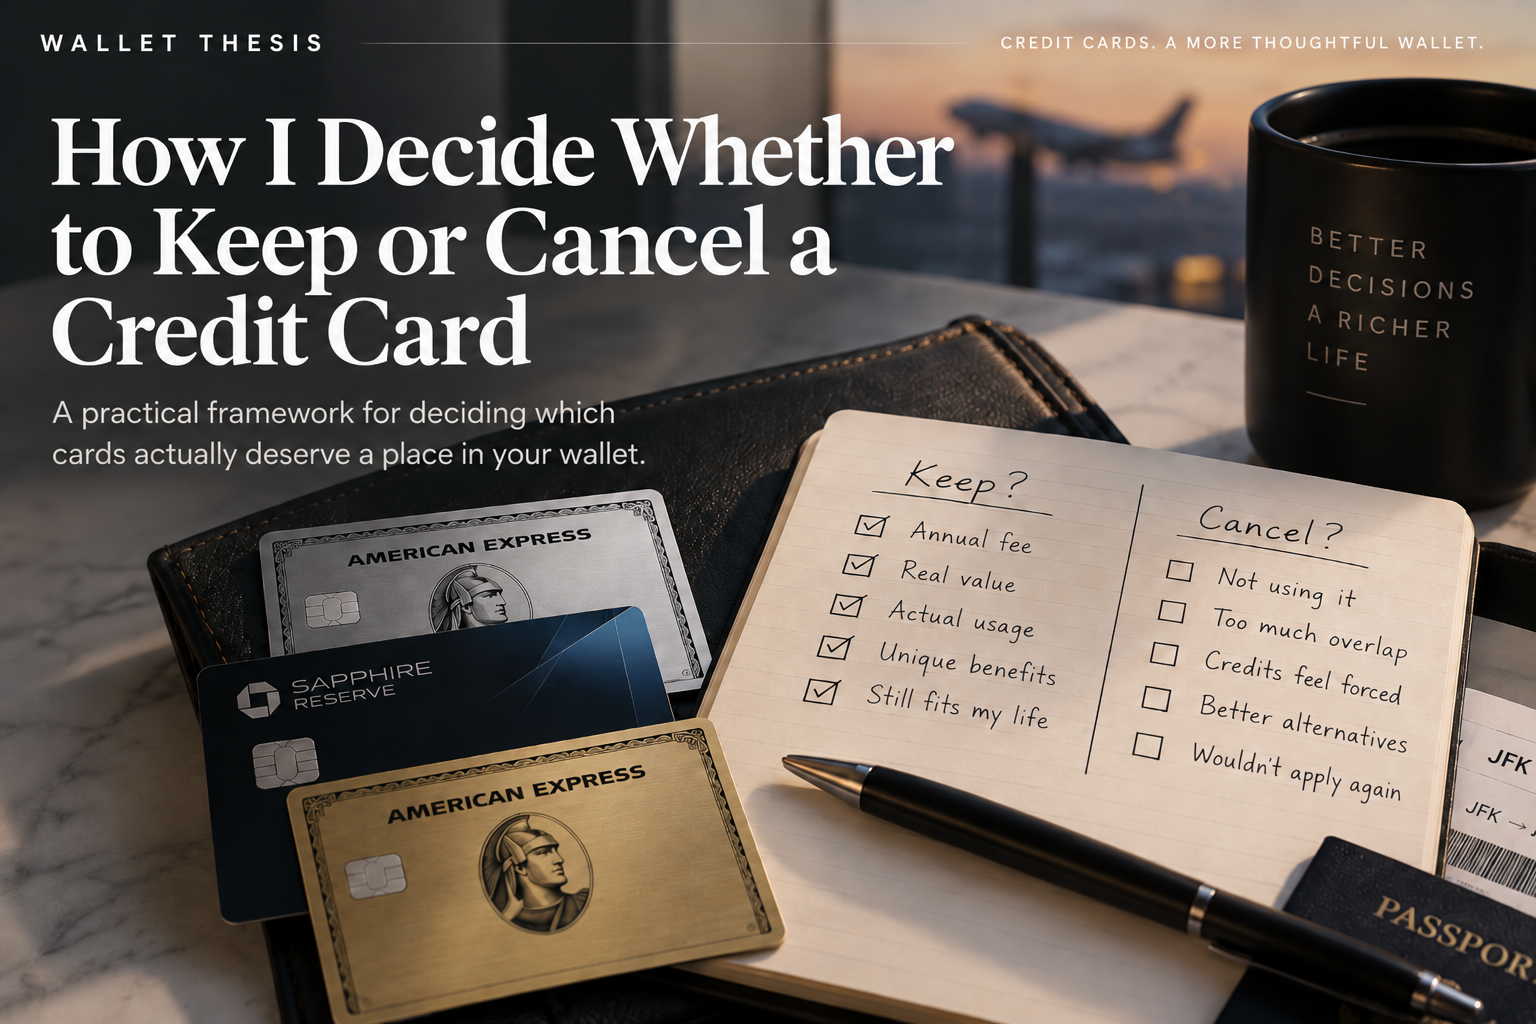
Credit card annual fees have become increasingly easy to justify on paper.
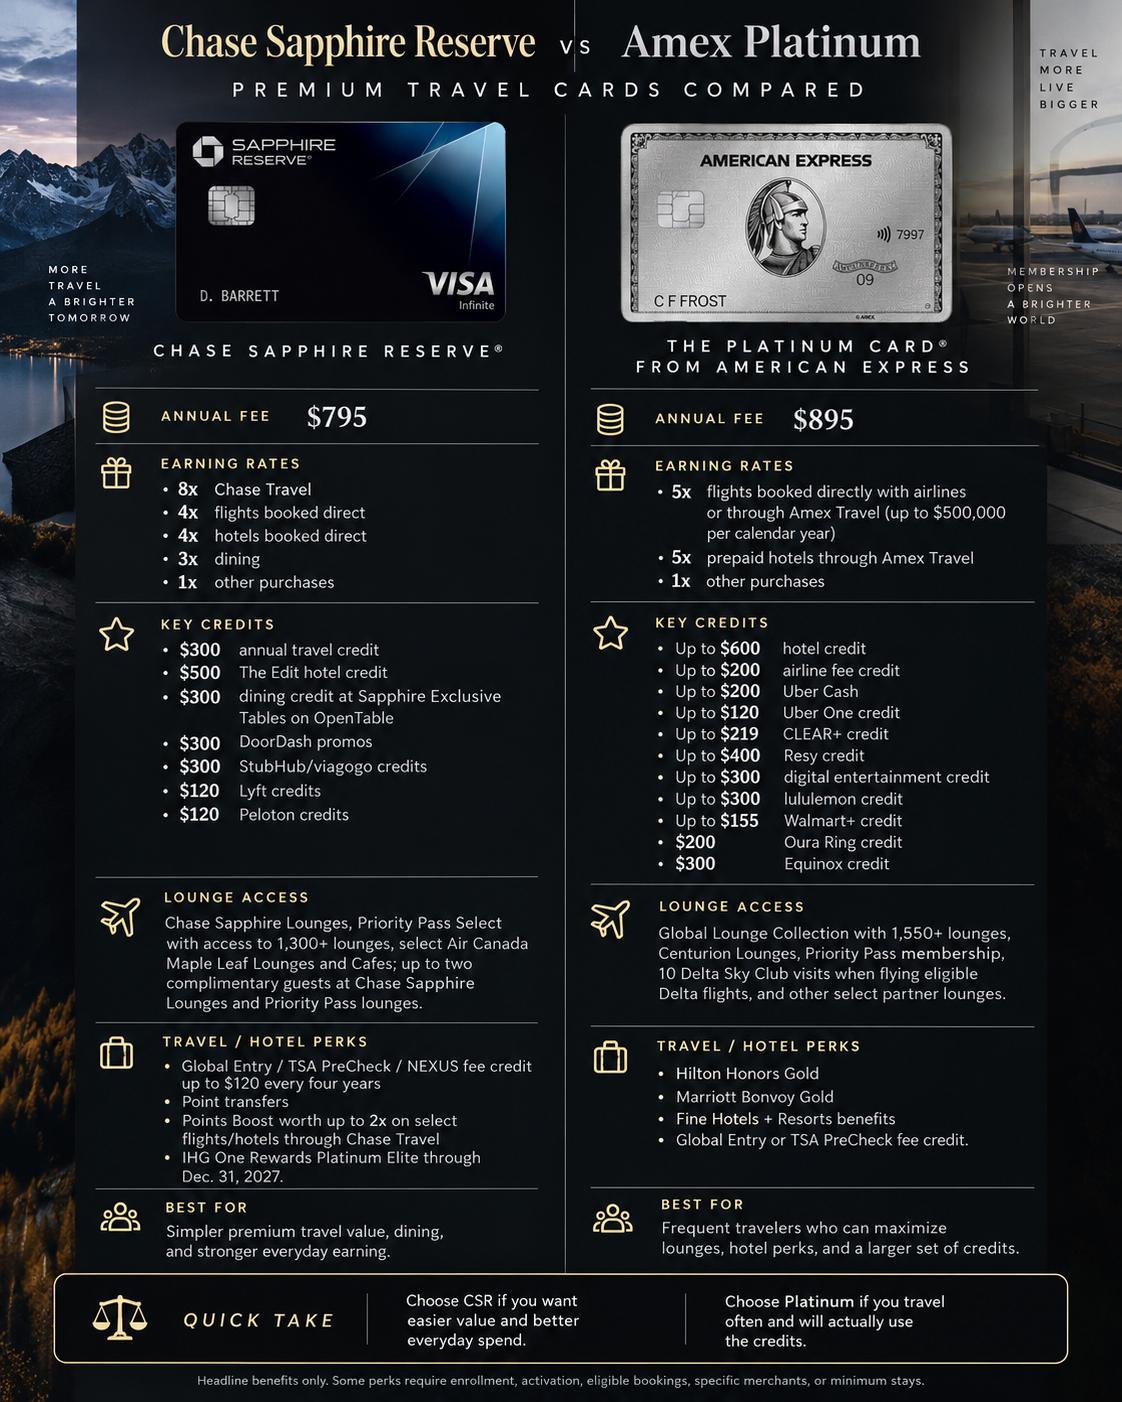
A card might charge $395, $550, $695, or even more than $800 a year, then advertise hundreds or thousands of dollars in credits, memberships, protections, and perks.
The math can look obvious.
Pay $700. Get $1,200 in value.
Keep the card.
But that isn’t how I think about it.
I’ve opened more than 60 credit cards over the years, and one of the biggest lessons I’ve learned is that the value printed on a benefits page is not the same as the value I actually receive.
A $200 credit isn’t worth $200 to me if I would never have spent that money otherwise.
A lounge membership isn’t worth hundreds of dollars if I barely visit lounges.
And a card that technically “pays for itself” can still be a bad card for my wallet if I have to constantly change my behavior just to justify keeping it.
So when an annual fee comes due, I use a much simpler framework.
1. Start With the Annual Fee
The annual fee is real money.
That sounds obvious, but I think it gets lost surprisingly often when people talk about premium credit cards.
If a card costs $695 a year, I start at negative $695.
I don’t start with the welcome bonus.
I don’t start with how much the points might theoretically be worth.
And I don’t count every possible benefit at face value.
The card has to earn its way back from that starting point.
That mindset makes the evaluation much clearer.
2. Count Credits I Would Have Used Anyway
This is probably the most important rule in my entire framework.
I give full value to a credit only when it replaces spending I was already going to make.
If I already spend $15 every month on a service and my credit card reimburses that $15, that is close to real savings.
If I already book hotels through a certain program and the card gives me an annual hotel credit, that can also be meaningful.
But if a card gives me $200 toward something I never normally buy, I don’t automatically value that benefit at $200.
Maybe I value it at $50.
Maybe I value it at zero.
That doesn’t mean the benefit is bad.
It just means it isn’t worth the same amount to every cardholder.
This is where a lot of annual-fee math becomes misleading.
People often total every benefit listed by the issuer and conclude that a card with a $700 annual fee provides $1,400 in value.
Technically, maybe.
Personally, maybe not.
3. Discount Credits That Require Me to Change My Behavior
Some credit card benefits save money.
Others encourage spending.
There is a difference.
If I have to remember to place an order every month, shop with a retailer I normally wouldn’t use, or book through a portal I dislike just to avoid “wasting” a credit, I discount that benefit heavily.
The more effort a benefit requires, the less valuable it becomes to me.
I call this the friction cost.
The friction may not appear on a statement, but it is still real.
It can mean:
- remembering monthly deadlines
- tracking multiple credits
- changing where I shop
- paying more than I normally would
- booking through a specific portal
- keeping a card in my wallet purely to trigger one benefit
If managing a card starts feeling like a part-time job, the card is probably becoming less valuable than the spreadsheet suggests.
4. Consider What I Actually Earn From Spending
Benefits are only part of the equation.
I also look at how the card performs when I actually use it.
Some cards justify their place in my wallet because they earn very well in categories where I spend significant money.
Dining.
Groceries.
Travel.
Transit.
Online shopping.
Whatever the category may be.
But I try not to fall into the trap of obsessing over tiny differences in earning rates.
The difference between earning 3 points per dollar and 4 points per dollar can matter.
But if I have to carry another card, remember another category, and pay another annual fee to get that extra point, I have to ask whether the complexity is worth it.
This is one of the reasons I increasingly prefer a smaller wallet.
Fewer, better cards.
I would rather have a coherent system than theoretically maximize every transaction.
5. Look for Overlap
A card can be good and still be unnecessary.
This is especially common with premium travel cards.
Maybe two cards both offer:
- airport lounge access
- travel protections
- hotel benefits
- statement credits
- rental car coverage
- premium customer service
Individually, both cards might be excellent.
Together, much of the value may overlap.
So I ask a simple question:
What does this card give me that I do not already have?
If the answer is mostly redundant benefits, the annual fee becomes harder to justify.
This is also why I don’t think everyone needs to build a large “credit card ecosystem.”
More cards do not automatically create more value.
Sometimes they just create more annual fees.
6. Ignore the Welcome Bonus When Deciding Whether to Keep the Card
A welcome bonus can be a great reason to open a credit card.
It is usually a terrible reason to keep one.
These are two completely different decisions.
When I apply for a card, I might decide that a large signup bonus makes the first year worthwhile.
But when the second annual fee arrives, the bonus is gone.
At that point, the card needs to justify itself based on its ongoing value.
This distinction matters because a card can be an excellent card to open and a mediocre card to keep.
There is nothing wrong with that.
The mistake is assuming that because a card was worth applying for, it must also be worth holding indefinitely.
7. Ask What I Lose If I Cancel
Cancellation isn’t always an automatic decision just because the math looks slightly negative.
There are other things I consider.
Will I lose a useful transfer partner ecosystem?
Will canceling affect how I redeem points?
Am I giving up a benefit that would be expensive to replace?
Is there a downgrade option that preserves the account without the annual fee?
Would I need to reapply later and potentially lose access to a product?
These factors don’t automatically justify keeping a card, but they belong in the analysis.
Sometimes the best decision is not “keep” or “cancel.”
It is downgrade.
8. Ask the Final Question: Would I Apply for This Card Again Today?
This may be the simplest test of all.
Imagine the card disappeared from your wallet tonight.
Tomorrow morning, the issuer offers you the same card again.
Same annual fee.
Same benefits.
Same earning rates.
Would you apply?
If the answer is immediately yes, the card is probably doing its job.
If the answer is no, but you still feel reluctant to cancel it, that may be inertia.
I think this question cuts through a lot of emotional attachment to cards.
Past signup bonuses don’t matter.
Prestige doesn’t matter.
How long you’ve had the card doesn’t necessarily matter.
What matters is whether the product makes sense for your life today.
My Rule: Make Every Annual Fee Prove Itself
I am not against annual fees.
Quite the opposite.
I’ve paid annual fees on credit cards for more than a decade, and some of my favorite cards have expensive annual fees.
A good premium credit card can absolutely be worth paying for.
But the fee should have a purpose.
I don’t want to keep a card because I can construct a spreadsheet showing $1,000 of theoretical value.
I want the card to save me money, improve how I travel, earn meaningful rewards, or make something I already do noticeably better.
Preferably more than one of those things.
That is ultimately the philosophy behind Wallet Thesis.
The goal is not to collect as many valuable credit cards as possible.
The goal is to build a wallet where every card has a reason to be there.
And when a card no longer has one, I’m comfortable letting it go.