There's a point in the credit card hobby where maximizing rewards stops feeling rewarding.
You start with a simple idea.
Use a credit card for purchases you're already making, earn points or cash back, and get something in return.
Then you discover bonus categories.
Dining earns 4x. Groceries earn 3x. Travel earns 5x. Certain purchases might earn even more if you use the right card, book through the right portal, or activate the right offer.
Before long, something as ordinary as buying lunch becomes a decision about which card produces the highest return.
I know because I've spent nearly 20 years thinking about credit cards.
I've opened more than 60 of them.
And while I still appreciate a good rewards structure, I've become much less interested in optimizing every transaction.
Because the goal isn't to earn the most points possible. It's to get the most value out of the money I was already going to spend.
Those are two very different things.
The Problem With Perfect Optimization
There's no shortage of advice about building the perfect credit card setup.
One card for restaurants.
Another for groceries.
A different card for gas.
Something for travel.
Maybe a rotating-category card for quarterly bonuses.
And perhaps a flat-rate card to catch everything else.
Mathematically, it can make sense.
If every purchase goes on the card with the highest earning rate, your overall rewards improve.
But that calculation leaves something out.
The effort required to maintain the system.
Every additional card creates another decision.
Every bonus category is something to remember.
Every quarterly activation is another task.
Every new rewards program adds another balance to manage.
At some point, the wallet becomes a project.
And I don't necessarily want another project.
How Much Is That Extra Point Really Worth?
Consider a simple example.
You're spending $1,000 a month on purchases that don't fall into any special bonus category.
One card earns 2% back.
Another earns 3%.
The difference is $10 a month.
That's $120 a year.
Would I rather earn $120 more for doing exactly the same thing?
Of course.
But what if earning that extra $120 requires opening another card, tracking another account, managing another rewards program, and remembering to use a different payment method?
Now the calculation becomes more interesting.
For some people, that effort is absolutely worth $120.
For others, it isn't.
And neither answer is necessarily wrong.
What matters is recognizing that the additional rewards aren't completely free if they require time and attention.
The highest earning rate isn't always the highest-value decision.
Why My Wallet Has Become More Intentional
These days, I think about my cards in terms of roles rather than individual spending categories.
I don't need every card to compete for every purchase.
I want each one to do something particularly well.
Some cards are useful because they earn strong rewards on everyday spending.
Others justify themselves through benefits rather than spending.
And some exist primarily because they offer something that isn't easily replicated elsewhere in my wallet.
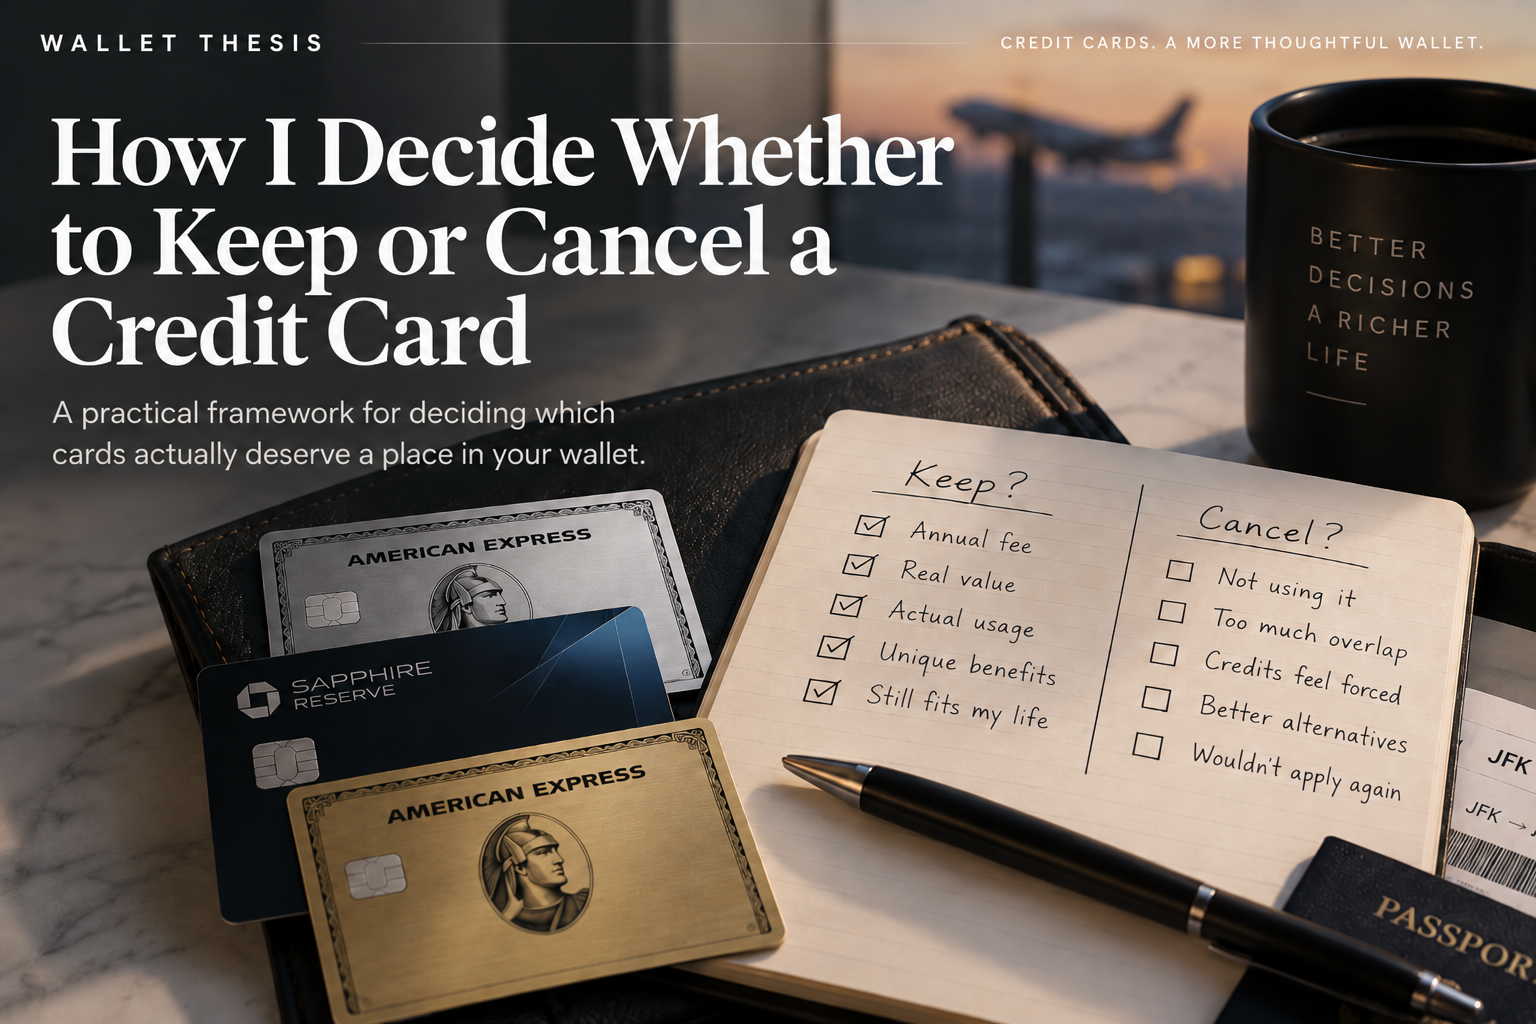
The American Express Gold is a good example of the first category.
It's a card that naturally fits expenses like dining and groceries.
I don't have to invent reasons to use it.
The Chase Sapphire Reserve serves a different purpose.
It's a premium card I genuinely enjoy using, particularly because its travel and dining benefits fit expenses I already have.
Then there's the American Express Platinum.
I've written before about why I view the Platinum differently from the Sapphire Reserve.
It's less about everyday spending and more about the collection of benefits that justify keeping the account open.
These cards aren't interchangeable.
And that's exactly the point.
A well-designed wallet doesn't need five cards competing to do the same job.
It needs a small number of cards with clear reasons to exist.
Points Are Only Valuable When You Use Them
Another issue with maximizing rewards is that earning points and realizing their value are not the same thing.
It's easy to celebrate earning 100,000 points.
It's harder to determine what those points are actually worth.
You might see someone claim that a particular rewards currency is worth two cents per point, or even more.
Sometimes that's achievable.
But the valuation means very little unless you can realistically redeem your points at that rate.
A premium international flight might produce an impressive cents-per-point calculation.
That doesn't automatically make it a good redemption for someone who wouldn't otherwise purchase that flight.
And a points balance sitting unused for years isn't doing much for your financial life.
I've become increasingly interested in rewards that offer practical, repeatable value.
Sometimes that means transferring points for travel.
Sometimes it means accepting a straightforward cash redemption.
And sometimes it means recognizing that flexibility matters more than chasing the theoretically highest redemption value.
I'd rather realize a good return than endlessly wait for a perfect one.
There's a Difference Between Enjoying the Hobby and Being Controlled by It
I still enjoy credit cards.
I like learning about new products.
I like comparing rewards structures.
I like understanding how different issuers position their premium cards.
And I'll still pay attention when a compelling signup bonus or genuinely useful benefit appears.
I'm not arguing that everyone should abandon rewards optimization.
The hobby itself can be enjoyable.
But there's a distinction between choosing to spend time on something because you enjoy it and feeling obligated to spend time on it because you don't want to lose a few dollars of value.
I don't want to feel like I've made a mistake because I used a 2x card instead of a 3x card.
I don't want to spend more money just to activate a credit.
And I don't want to open another account simply because someone calculated that it could produce an extra $75 a year under ideal conditions.
There will always be another offer.
Another multiplier.
Another limited-time promotion.
Another supposedly perfect setup.
Trying to capture everything is an endless exercise.
The Best Wallet Is the One You Actually Want to Use
After opening more than 60 credit cards, I could probably build a wallet that maximizes nearly every major spending category.
But I don't think that would necessarily make it better.
I've come to appreciate predictability.
I like knowing which cards I want to use without constantly checking a spreadsheet.
I like benefits that are straightforward to redeem.
I like having a reason for every card I keep.
And I like being able to ignore an offer without feeling as though I'm missing out.
That last part might be the biggest change in how I approach credit cards.
I used to think there was always another opportunity to optimize.
Now I recognize that sometimes the best decision is to do nothing.
Keep the card that works.
Use the benefits that make sense.
Redeem the points when they're useful.
And don't overcomplicate the rest.
My Thesis
Credit card rewards are supposed to improve the economics of spending you were already going to do.
They're not supposed to become the reason you spend.
There's nothing wrong with maximizing points when it's easy, convenient, and genuinely worthwhile.
But maximum rewards and maximum value aren't always the same thing.
The difference is what it takes to get there.
I've reached a point where I'd rather have a wallet that works exceptionally well with minimal effort than one that performs perfectly only when I constantly manage it.
That doesn't mean I've stopped caring about rewards.
It means I've become more selective about which rewards are worth caring about.
Because the best credit card strategy isn't the one that earns the most points.
It's the one that makes the most sense for the person using it.
And increasingly, I think that means knowing when enough optimization is enough.